Debit or Credit? Pick a Card
June 22, 2020
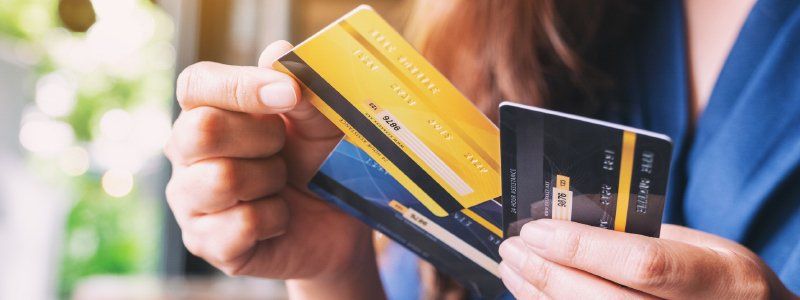
Americans use debit cards more often than credit cards, but they tend to use credit cards for higher-dollar transactions. The average value of a debit-card transaction in 2018 was just $36, while credit-card transactions averaged $89.(1)
This usage reflects fundamental differences between the two types of cards. A debit card acts like a plastic check and draws directly from your checking account, whereas a credit-card transaction is a loan that remains interest-free only if you pay your monthly bill on time. For this reason, people may use a debit card for regular expenses and a credit card for "extras." However, when deciding which card to use, you should be aware of other differences.
Fraud protection. In general, you are liable for no more than $50 in fraudulent credit-card charges. For debit cards, a $50 limit applies only if a lost card or PIN is reported within 48 hours. The limit is $500 if reported within 60 days, with unlimited liability after that. A credit card may be safer in higher-risk situations, such as when shopping online, when the card will leave your sight (as in a restaurant), or when you are concerned about the security of a card reader. If you regularly use a debit card in these situations, you may want to maintain a lower checking balance and keep most of your funds in savings.
Merchant disputes. You can dispute a credit-card charge before paying your bill and shouldn't have to pay it while the charge is under dispute. Disputing a debit-card charge can be more difficult when the charge has been deducted from your checking account, and it may take some time before the funds are returned.
Rewards and extra benefits. Debit cards offer little or no additional benefits, whereas some credit cards offer cash-back rewards, and major cards may include extra benefits such as travel insurance, extended warranties, and secondary collision and theft coverage for rental cars (up to policy limits). Of course, if you do not pay your credit-card bill in full each month, the interest you pay can outweigh any financial rewards or benefits.
Credit history. Using a credit card can affect your credit score positively or negatively, depending on how you use it. A debit card does not affect your credit score.
Considering the additional protections and benefits, a credit card may be a better choice in some situations — but only if you pay your monthly bill on time.
(1) Federal Reserve, 2019
All Securities Through Money Concepts Capital Corp., Member FINRA / SIPC
11440 North Jog Road, Palm Beach Gardens, FL 33418 Phone: 561.472.2000
Copyright 2010 Money Concepts International Inc.
Investments are not FDIC or NCUA Insured
May Lose Value - No Bank or Credit Union Guarantee
This communication is strictly intended for individuals residing in the state(s) of MI. No offers may be made or accepted from any resident outside the specific states referenced.
Prepared by Broadridge Advisor Solutions Copyright 2020.
Learn how ghost tapping scams work, the risks tied to tap-to-pay cards and mobile wallets, and simple steps to help protect your money and personal information.
Learn how a Health Savings Account can offer tax advantages, help cover qualified medical expenses, and build funds for health-care costs later in life.
Learn how workplace retirement plans work, including target-date funds, stock and bond funds, company stock, diversification, and portfolio rebalancing.
Learn how claiming age affects Social Security retirement benefits, from reduced payments at 62 to delayed retirement credits available through age 70.