Key Retirement and Tax Numbers for 2021
Every year, the Internal Revenue Service announces cost-of-living adjustments that affect contribution limits for retirement plans and various tax deduction, exclusion, exemption, and threshold amounts. Here are a few of the key adjustments for 2021.
Estate, Gift, and Generation-Skipping Transfer Tax
- The annual gift tax exclusion (and annual generation-skipping transfer tax exclusion) for 2021 is $15,000, the same as in 2020.
- The gift and estate tax basic exclusion amount (and generation-skipping transfer tax exemption) for 2021 is $11,700,000, up from $11,580,000 in 2020.
Standard Deduction
A taxpayer can generally choose to itemize certain deductions or claim a standard deduction on the federal income tax return. In 2021, the standard deduction is:
- $12,550 (up from $12,400 in 2020) for single filers or married individuals filing separate returns
- $25,100 (up from $24,800 in 2020) for married individuals filing joint returns
- $18,800 (up from $18,650 in 2020) for heads of households
The additional standard deduction amount for the blind or aged (age 65 or older) in 2021 is:
- $1,700 (up from $1,650 in 2020) for single filers and heads of households
- $1,350 (up from $1,300 in 2020) for all other filing statuses
Special rules apply if you can be claimed as a dependent by another taxpayer.
IRAs
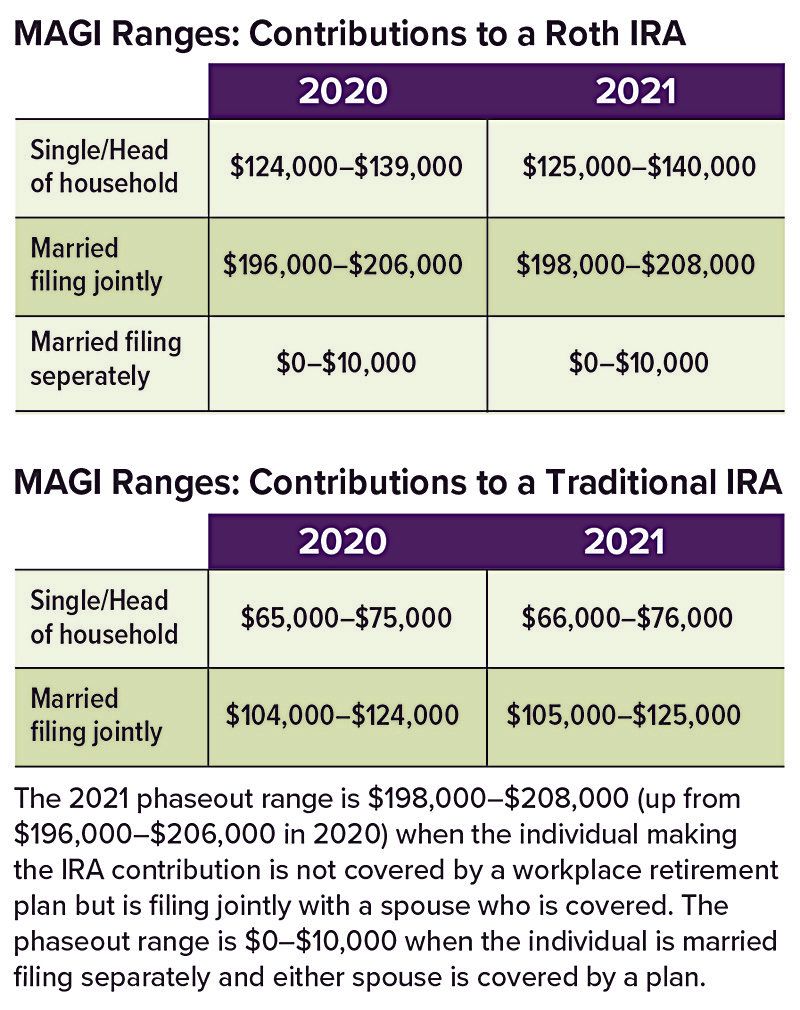
The combined annual limit on contributions to traditional and Roth IRAs is $6,000 in 2021 (the same as in 2020), with individuals age 50 and older able to contribute an additional $1,000. The limit on contributions to a Roth IRA phases out for certain modified adjusted gross income (MAGI) ranges. For individuals who are covered by a workplace retirement plan, the deduction for contributions to a traditional IRA also phases out for certain MAGI ranges. (The limit on nondeductible contributions to a traditional IRA is not subject to phase-out based on MAGI.)
Employer Retirement Plans
- Employees who participate in 401(k), 403(b), and most 457 plans can defer up to $19,500 in compensation in 2021 (the same as in 2020); employees age 50 and older can defer up to an additional $6,500 in 2021 (the same as in 2020).
- Employees participating in a SIMPLE retirement plan can defer up to $13,500 in 2021 (the same as in 2020), and employees age 50 and older can defer up to an additional $3,000 in 2021 (the same as in 2020).
Kiddie Tax: Child's Unearned Income
Under the kiddie tax, a child's unearned income above $2,200 in 2021 (the same as in 2020) is taxed using the parents' tax rates.
All Securities Through Money Concepts Capital Corp., Member FINRA / SIPC
11440 North Jog Road, Palm Beach Gardens, FL 33418 Phone: 561.472.2000
Copyright 2010 Money Concepts International Inc.
Investments are not FDIC or NCUA Insured
May Lose Value - No Bank or Credit Union Guarantee
This communication is strictly intended for individuals residing in the state(s) of MI. No offers may be made or accepted from any resident outside the specific states referenced.
Prepared by Broadridge Advisor Solutions Copyright 2020.